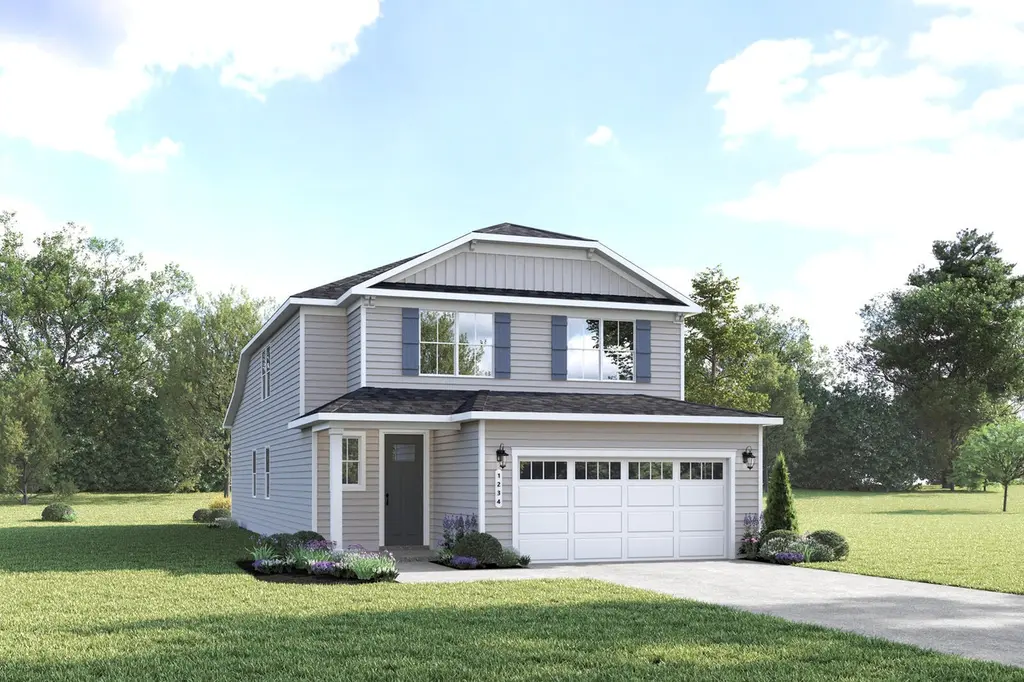
201 E Branch Dr
Huger, SC 29450
$479,990D-
4 bd · 2.5 ba ·
2,197 sqft ·
Built 2026
· SingleFamily
· Active
· 113 DOM
Cashflow @ list (25.0% down · 7.5%)
Estimated rent
$3,368/mo
Mortgage (P&I)
−$2,517
Tax + insurance
−$866
HOA
−$75
Vac / Maint / Mgmt
−$707
Net cashflow
$-798/mo
Annual
$-9,579/yr
Cap rate
4.46%
Cash-on-cash
-6.53%
DSCR
0.71
1% rule
0.70%
Cash to close
$134,397
Investor read
- This is a 4-bed/2.5-bath single-family listed at $480k. Condition is rated excellent.
- At list price, monthly cash flow is $-798 ($-10k/yr) — negative.
- To cash-flow at today's rent, offer at most $364k (24.1% below list).
- To meet the 1% rule (rent ≥ 1% of price), the offer needs to be $337k (29.8% below list).
- It's been on market 113 days — a 9% lower offer ($437k) is reasonable based on typical stale-listing flexibility.
- Recommended offer: $337k (29.8% below list) — sets the bar for 1% rule.
- Local home prices are declining (-1.1%/yr); year-one equity from $3k of loan paydown is wiped out by about $5k of value loss. Plan a longer hold.
- Location reads: area grade D — affects rentability + tenant quality, not the cash-flow math above.
- Berkeley 01 (suburban): math 35% / reading 48% proficiency, ranked #30 of 80 in SC (top 38%) — families likely to look elsewhere, expect single-tenant / working-renter base with shorter leases.
- Zoned schools: Cainhoy Elementary (math 2% / reading 12%, grade F, #594 of 597 statewide, top 100%, 154 students, 100% FRL); Philip Simmons Middle (math 31% / reading 48%, grade F, #82 of 229 statewide, top 37%, 428 students, 35% FRL); Philip Simmons High (math 42% / reading 92%, grade B, #73 of 196 statewide, top 41%, 771 students, 21% FRL) — zoned schools at 52% FRL track the district average.
- Watch-outs: flood insurance adds $66/mo.
- Market conditions: 98 active listings in the ZIP; 3,183 units permitted in Berkeley County in 2024 (580 in 5+ unit buildings).
- Berkeley County population projected at +48% by 2050 — long-run rental-demand tailwind backs the buy-and-hold thesis.
- 2 sale attempts with the ask held roughly flat each time — persistent listings suggest the price (not the market) is what's stuck; bring a comps-based counter.
- Climate carrying-cost: severe flood risk; severe wind risk, 98% chance of damaging wind over 30y; extreme-heat days projected 7→18/yr by 2055 (HVAC capex compounding) — expect insurance premiums to compound above CPI over the hold.
- Cap rate 4.5% vs local median 3.7% in Huger — meaningfully above typical; check what's discounted (condition, days-on-market, listing class) to confirm the premium yield is real.
- At $3,368/mo this rent would consume 77% of the median local household income ($52k/yr) — very limited rent-growth headroom before tenants either downsize or default.
Questions for listing agent
- What do current leases actually rent for vs. the listed asking? Can we see a recent rent roll and the last 12 months of T-12 income?
- It's been on market 113 days. Have you received any prior offers? Is the seller open to a 30% concession, seller financing, or rate buy-down credit?
- What's the actual annual flood-insurance premium (NFIP or private), and is the property in a SFHA with mandatory coverage?
- What does the HOA fee cover, when was the last increase, and are there any pending special assessments or reserve-fund shortfalls?
- Why hasn't it sold? Are there any deal-killer items the seller is aware of (foundation, flood, title, zoning, code violations)?
- Is there a deadline driving the sale (1031 exchange, divorce, estate, relocation)? That informs how much negotiation room exists.
- The area grade is low — what's the realistic commute time and amenity access for the typical tenant pool here? Any planned neighborhood developments (good or bad) we should know about?
- What's the average days-on-market for RENTAL listings here right now (not sales)? A rising rental-DOM trend means longer vacancies and softer asking-rent achievability than the comps imply.
CashFlowRE · CFR-31D2NZ373G5HMX
· Data 7 h ago
cashflowre.app · 2026-05-29