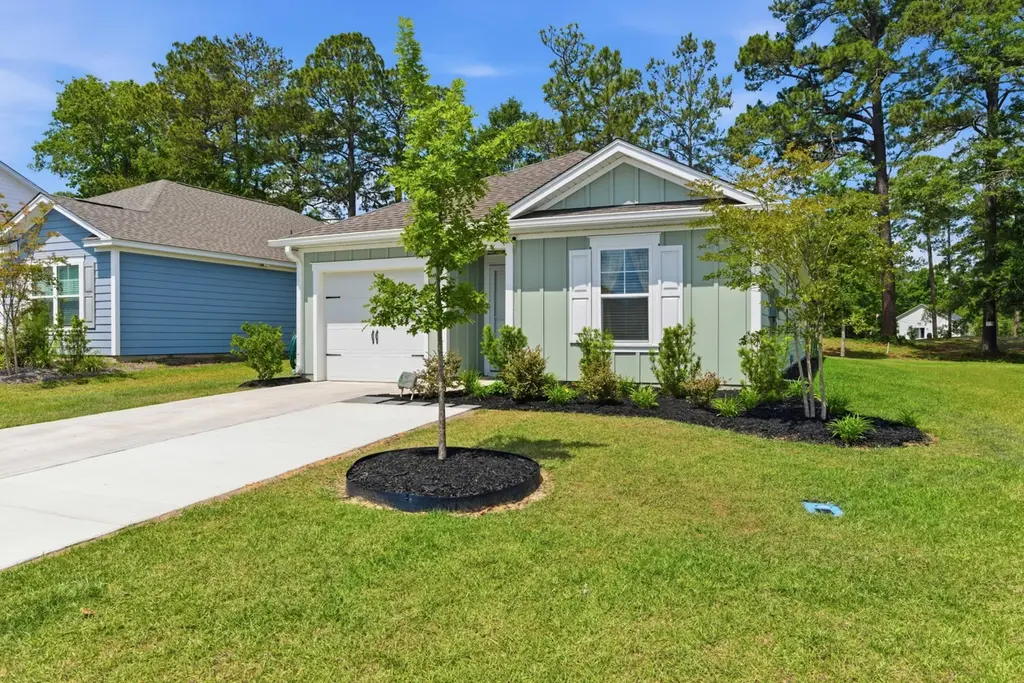
126 Congaree Ct
Santee, SC 29142
$250,000C-
4 bd · 2.0 ba ·
1,482 sqft ·
Built 2024
· SingleFamily
· Active
· 51 DOM
Cashflow @ list (25.0% down · 7.5%)
Estimated rent
$2,178/mo
Mortgage (P&I)
−$1,311
Tax + insurance
−$417
HOA
−$43
Vac / Maint / Mgmt
−$457
Net cashflow
$-50/mo
Annual
$-599/yr
Cap rate
6.05%
Cash-on-cash
-0.86%
DSCR
0.96
1% rule
0.87%
Cash to close
$70,000
Investor read
- This is a 4-bed/2.0-bath single-family listed at $250k. Condition is rated good.
- At list price, monthly cash flow is $-50 ($-599/yr) — negative.
- To cash-flow at today's rent, offer at most $243k (2.9% below list).
- To meet the 1% rule (rent ≥ 1% of price), the offer needs to be $218k (12.9% below list).
- It's been on market 51 days — a 3% lower offer ($242k) is reasonable based on typical stale-listing flexibility.
- Recommended offer: $218k (12.9% below list) — sets the bar for 1% rule.
- In year one you build about $10k of equity ($2k loan paydown + $9k appreciation (3.5% local appreciation)).
- Location reads 61/100 on livability (#202 in SC) — a middle-class / working-renter tenant base. Strengths: cost of living A+, health & safety A+; Watch: crime F, amenities F, commute F.
- Zoned schools: Elloree Elementary (math 10%, 387 students, 100% FRL).
- Market conditions: 183 active listings in the ZIP; 9 comparable units currently listed for rent nearby; rentals lingering (median 63d on market — plan ~5-8 weeks vacancy on turnover, expect pricing pressure); 56% of comp listings sitting > 30 days — soft ceiling on asking rent; 87 units permitted in Orangeburg County in 2024 (0 in 5+ unit buildings).
- Orangeburg County population projected at -27% by 2050 — secular population decline; favor cash flow + early exit over multi-decade hold.
- 4 sale attempts with the ask held roughly flat each time — persistent listings suggest the price (not the market) is what's stuck; bring a comps-based counter.
- At projected returns (3.5% appreciation + 3.0% rent growth), your $70k cash investment doubles in ~6 years — after that, you're playing with house money.
- By year 4, paydown + projected appreciation supports a ~$35k cash-out refi (75% LTV) — recoverable capital for the next deal without selling this one.
- Cap rate 6.1% vs local median 5.0% in Santee — meaningfully above typical; check what's discounted (condition, days-on-market, listing class) to confirm the premium yield is real.
- At $2,178/mo this rent would consume 52% of the median local household income ($51k/yr) (locally 31% of renters already pay >50% of income on rent) — very limited rent-growth headroom before tenants either downsize or default.
Questions for listing agent
- What do current leases actually rent for vs. the listed asking? Can we see a recent rent roll and the last 12 months of T-12 income?
- It's been on market 51 days. Have you received any prior offers? Is the seller open to a 13% concession, seller financing, or rate buy-down credit?
- What does the HOA fee cover, when was the last increase, and are there any pending special assessments or reserve-fund shortfalls?
- Is there a deadline driving the sale (1031 exchange, divorce, estate, relocation)? That informs how much negotiation room exists.
- Schools are D-rated, which usually means shorter tenancies and higher turnover. Who's the typical renter profile here, and what's been the actual vacancy rate?
- Crime grade is F in this area — have there been break-ins, vandalism, or insurance claims at this property in the last 3 years? What carrier currently insures it and at what premium?
- What's the average days-on-market for RENTAL listings here right now (not sales)? A rising rental-DOM trend means longer vacancies and softer asking-rent achievability than the comps imply.
- What's the recent tenant-quality profile in this submarket — average credit score on applications, eviction rate, late-payment / NSF rate, and stable-employment percentage? A property-management company in the area should have these aggregated.
CashFlowRE · CFR-HWQW6ACHNFQQ33
· Data 2 h ago
cashflowre.app · 2026-05-29