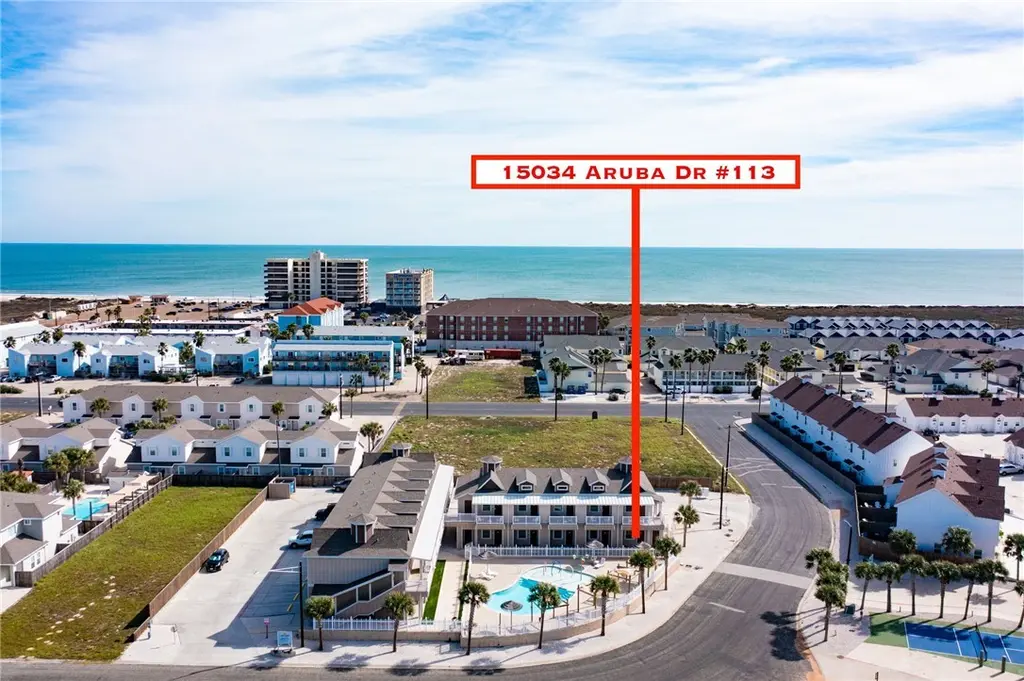
15034 Aruba Dr #113
Corpus Christi, TX 78418
$189,000F
1 bd · 1.0 ba ·
495 sqft ·
Built 2019
· Condo
· Active
· 16 DOM
Cashflow @ list (25.0% down · 7.5%)
Estimated rent
$1,192/mo
Mortgage (P&I)
−$991
Tax + insurance
−$821
HOA
−$563
Vac / Maint / Mgmt
−$250
Net cashflow
$-1,434/mo
Annual
$-17,207/yr
Cap rate
-0.10%
Cash-on-cash
-22.84%
DSCR
-0.02
1% rule
0.63%
Cash to close
$52,920
Investor read
- This is a 1-bed/1.0-bath condo listed at $189k. Condition is rated good.
- At list price, monthly cash flow is $-1k ($-17k/yr) — negative.
- Rent doesn't cover operating costs at any purchase price — skip.
- To meet the 1% rule (rent ≥ 1% of price), the offer needs to be $119k (36.9% below list).
- It's been on market 16 days — a 2% lower offer ($186k) is reasonable based on typical stale-listing flexibility.
- Recommended offer: $119k (36.9% below list) — sets the bar for 1% rule.
- Local home prices are declining (-3.0%/yr); year-one equity from $1k of loan paydown is wiped out by about $6k of value loss. Plan a longer hold.
- Location reads 78/100 on livability (#66 in TX, #2,404 nationally) — a middle-class / working-renter tenant base. Strengths: commute A+, cost of living A+, housing A+; Watch: crime F.
- Zoned schools: Flour Bluff El (math 40% / reading 42%, grade F, #1,462 of 4,322 statewide, top 34%, 759 students, 53% FRL); Flour Bluff J H (math 45% / reading 53%, grade C-, #378 of 1,662 statewide, top 23%, 919 students, 46% FRL); Flour Bluff H S (math 33% / reading 62%, grade D, #583 of 1,632 statewide, top 36%, 1,958 students, 40% FRL).
- Watch-outs: flood insurance adds $427/mo; HOA is 47% of rent.
- Market conditions: Rents soft (-0.6%/yr); 991 active listings in the ZIP; solid renter incomes; 1,397 units permitted in Nueces County in 2024 (47 in 5+ unit buildings).
- Nueces County population projected at +36% by 2050 — long-run rental-demand tailwind backs the buy-and-hold thesis.
- Climate carrying-cost: in FEMA flood zone AE (mandatory federal flood insurance); severe wind risk, 99% chance of damaging wind over 30y; extreme-heat days projected 8→33/yr by 2055 (HVAC capex compounding) — expect insurance premiums to compound above CPI over the hold.
- Cap rate -0.1% vs local median 3.9% in Corpus Christi — below-typical yield; the buyer is paying a premium for something (appreciation thesis, condition, location) that the cap rate doesn't capture.
- This rent is only 15% of the median local income ($92k/yr) — well below the 30% rent-burden line; pricing power to push rent on renewal without tenant pushback.
Questions for listing agent
- What do current leases actually rent for vs. the listed asking? Can we see a recent rent roll and the last 12 months of T-12 income?
- What's the actual annual flood-insurance premium (NFIP or private), and is the property in a SFHA with mandatory coverage?
- What does the HOA fee cover, when was the last increase, and are there any pending special assessments or reserve-fund shortfalls?
- Any open or pending special assessments — roof, HVAC, plumbing, elevator, façade? What's the per-unit balance and payoff schedule, and is the seller paying it off at close or rolling it to the buyer?
- Is there a deadline driving the sale (1031 exchange, divorce, estate, relocation)? That informs how much negotiation room exists.
- Crime grade is F in this area — have there been break-ins, vandalism, or insurance claims at this property in the last 3 years? What carrier currently insures it and at what premium?
- The area grade is low — what's the realistic commute time and amenity access for the typical tenant pool here? Any planned neighborhood developments (good or bad) we should know about?
- What's the average days-on-market for RENTAL listings here right now (not sales)? A rising rental-DOM trend means longer vacancies and softer asking-rent achievability than the comps imply.
CashFlowRE · CFR-XKFJSM1MXAC8FY
· Data 2 h ago
cashflowre.app · 2026-05-29